Searching for student finance interest rates, the current SFE interest rate, or how Plan 5 interest works usually means one practical question: what rate applies to your loan plan for academic year 2026 to 2027, and does interest still build if you are studying, not working, or below the repayment threshold?
This FAQ-style guide explains Student Finance England (and wider UK plan) interest for 1 September 2026 to 31 August 2027, using the official announcement and repayment pages on GOV.UK. Related reading: when student loan repayments start in the UK, how much Maintenance Loan you could get, part-time Student Finance England, and Special Support Element explained. If benefits interact with your student support, see student finance on Universal Credit and benefits. For the broader mature funded-degree path, see university for mature students — this page stays on interest rates.
Not sure which plan or funded path fits you yet? Start with a free 2-minute check: check if you qualify for Student Finance England.
This article is general information for UK home students exploring Student Finance England. It is not advice from Student Finance England, the Student Loans Company, or the Department for Education. Your plan type, start date, residency and course decide which rules apply — always verify on GOV.UK and your Student Loans Company account. Figures below are from official GOV.UK guidance for the period 1 September 2026 to 31 August 2027 and may change. AF Education is not SFE or SLC.
Important: AF Education helps UK home students with the SFE and funded undergraduate / foundation-year application path. We cannot set or change interest rates, override an SLC calculation, or replace GOV.UK guidance. Only official sources confirm the rate on your balance. This service is not for international students.
Quick answer: 2026/27 interest snapshot
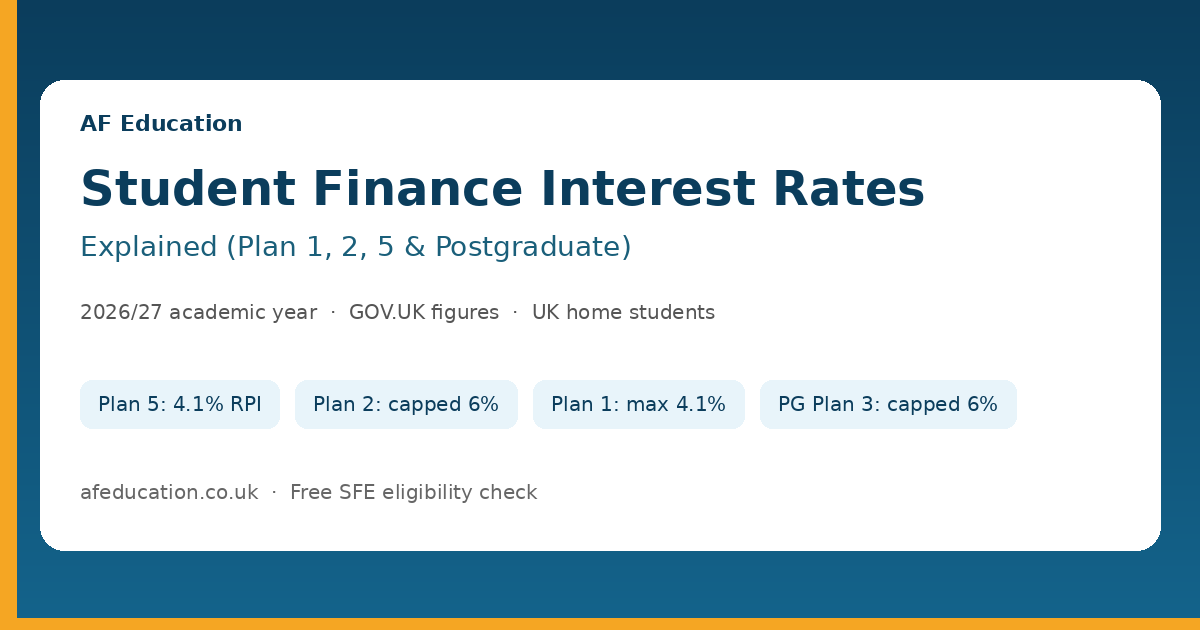
For 1 September 2026 to 31 August 2027, GOV.UK uses an applicable Retail Prices Index (RPI) of 4.1%. Headline caps and plan rates for that period include:
- Plan 5 (typical new England undergraduate starters from August 2023): RPI only = 4.1% (subject to any Policy Materiality Review / PMR cap rules GOV.UK applies)
- Plan 2: normally RPI to RPI+3% (4.1%–7.1%), but capped at 6% for this period (announced 7 April 2026)
- Plan 1: lower of RPI or Bank Base Rate + 1% → maximum 4.1% for this period
- Plan 3 (postgraduate): RPI+3% (7.1%) but capped at 6% for the same period
- Plan 4: 4.1% on the current displayed GOV.UK figures
- Mortgage-style loans: RPI 4.1%; deferment threshold £44,311
Source: GOV.UK student loans interest rates and repayment threshold announcement and GOV.UK: what you pay.
Tip: Interest and repayment are different clocks. Interest can still accrue while you study or while your income is below the repayment threshold. Repayments start under separate plan rules — see our guide on when repayments start.
Which plan am I on?
Your Student Loans Company account (and your Notification of Entitlement history) shows the plan. Broad England rules of thumb:
- Plan 5 — most new undergraduate starters in England from academic year 2023/24 (courses from August 2023)
- Plan 2 — many England undergraduates who started between 2012 and before Plan 5
- Plan 1 — older England and Wales undergraduate cohorts (pre-2012 style packages)
- Plan 3 — Postgraduate Master’s / Doctoral loans
- Plan 4 — Scottish plan (shown on GOV.UK what-you-pay tables)
If you are still choosing a funded undergraduate or foundation-year path, plan type is one reason to read GOV.UK carefully before you apply — and to use the free eligibility checker so you know whether SFE is even the right door.
Plan 5 interest (RPI only)
For most new England undergraduates from August 2023, Plan 5 interest is the cleanest headline: it tracks RPI only. For 1 September 2026 to 31 August 2027 that means 4.1%, subject to any PMR cap GOV.UK applies. There is no “while studying = RPI+3%” uplift of the Plan 2 style.
That does not mean the loan is free money. Interest still adds to the balance while you study and after you leave, including periods when you are not making repayments because you are below the Plan 5 repayment threshold of £25,000 a year (you repay 9% of income above that threshold under current GOV.UK what-you-pay rules).
Reassurance: Plan 5’s RPI-only design is usually simpler to explain than Plan 2’s income-variable post-study bands. Lock your personal rate to GOV.UK and your SLC statement — AF Education can help with funded-course fit and the SFE application path for free, while rates stay with official sources.
Plan 2 interest (with the 6% cap)
Plan 2 normally sits between RPI and RPI+3% (for this period that would be 4.1% to 7.1%). For 1 September 2026 to 31 August 2027, GOV.UK has capped Plan 2 at 6% (announced 7 April 2026).
While you are studying, Plan 2 interest is typically at the top of the range — RPI+3% — but still subject to the 6% cap in this period. After study, Plan 2 interest can vary with income. GOV.UK’s what-you-pay bands for this period describe post-study Plan 2 interest as:
- Income £29,385 or less → 4.1%
- Income £29,386 to £52,884 → 4.1% plus up to 1.9% (variable within the band)
- Income £52,885 or more → 6% (the cap for this period)
Plan 2’s repayment threshold for this period is £29,385 a year (9% above threshold). Again: being below the threshold stops or reduces repayments — it does not freeze interest by itself.
Plan 1, Plan 3, Plan 4 and mortgage-style
Plan 1 uses the lower of RPI or Bank of England base rate + 1%. For this period the maximum is 4.1%. The Plan 1 repayment threshold is £26,900 a year on current GOV.UK tables.
Plan 3 (postgraduate) would ordinarily be RPI+3% (7.1%) but is capped at 6% for 1 September 2026 to 31 August 2027. Postgraduate repayment threshold on GOV.UK what-you-pay is £21,000 a year at 6% above threshold (confirm your exact product on GOV.UK / SLC).
Plan 4 currently displays 4.1% on the interest tables. Mortgage-style loans use RPI 4.1%, with a deferment threshold of £44,311.
Do not invent other rates from blogs or social media — if a figure is not on GOV.UK for your plan and period, treat it as unverified.
Does interest apply if I am not working?
Yes. GOV.UK is clear that interest can still apply even if you are not working or your income is below the repayment threshold. That is one of the most misunderstood parts of student finance interest rates. Repayment thresholds control cash leaving your wages or Self Assessment; they do not automatically pause the interest clock.
If you are budgeting for Maintenance Loan living costs while studying, pair this page with how much Maintenance Loan and, if relevant, part-time SFE or special support.
Interest vs Tuition Fee Loan vs Maintenance Loan
Both Tuition Fee Loans and Maintenance Loans can attract interest under your plan rules. The SFE interest rate is about the balance on your student loan account — not a separate “fee interest” product for England undergraduates on standard plans. How much you borrow for fees versus living costs still matters for the size of the balance; how interest is calculated depends on plan type and the GOV.UK period rates above.
Applying still goes through the usual Student Finance England route. See how to apply for student finance step by step once you know the course and start date.
What AF Education helps with (for free)
AF Education — trading name of AF EDUCATION LONDON LTD (Companies House 08750757) — is at 47 Cavell Street, London E1 2BP · 020 7377 8844 · info@afeducation.co.uk. We offer free help for UK home students with SFE and funded undergraduate / foundation-year applications, including a free eligibility check. We do not set interest rates, guarantee loan outcomes, or replace GOV.UK or SLC decisions.
Frequently asked questions
What are student finance interest rates for 2026 to 2027?
For 1 September 2026 to 31 August 2027, applicable RPI is 4.1%. Plan 5 is typically 4.1% (RPI only). Plan 2 and Plan 3 postgraduate are capped at 6% for this period. Plan 1 maxes at 4.1%. Always confirm on GOV.UK for your plan.
What is the Plan 5 interest rate?
Plan 5 interest is RPI only. For this period that is 4.1%, subject to any PMR cap GOV.UK applies. New England undergraduate starters from August 2023 are typically on Plan 5.
Is Plan 2 interest really capped at 6%?
Yes for 1 September 2026 to 31 August 2027. GOV.UK announced the cap on 7 April 2026. Without the cap, Plan 2 would sit between RPI and RPI+3% (4.1%–7.1%). While studying, Plan 2 is usually at the top of the range but still subject to the 6% cap this year.
Do student loans still charge interest if I am below the repayment threshold?
Yes. Interest can still apply if you are not working or your income is below the repayment threshold. Thresholds affect repayments, not whether interest can accrue.
What are the repayment thresholds linked to these rates?
On current GOV.UK what-you-pay figures for this period: Plan 5 £25,000 a year (9% above); Plan 2 £29,385; Plan 1 £26,900; postgraduate £21,000 at 6% above. Mortgage-style deferment threshold is £44,311. Confirm your plan on GOV.UK / SLC.
How does Plan 2 post-study interest vary with income?
GOV.UK bands for this period: £29,385 or less → 4.1%; £29,386–£52,884 → 4.1% plus up to 1.9%; £52,885 or more → 6% (the period cap). Exact calculation sits with SLC using official rules.
Where should I check the official SFE interest rate?
Use the GOV.UK announcement for student loans interest rates and repayment thresholds, plus GOV.UK “what you pay”, and your Student Loans Company account. Do not rely on informal social posts for the rate on your balance.
What’s the first step if I am still deciding about university funding?
Run the free eligibility checker, note your likely start date (Plan 5 vs older plans), then apply via GOV.UK when ready. AF Education can help UK home students with funded-course choice and the SFE application path for free — only SFE and SLC confirm finance and interest on your account.
Next steps
Student finance interest rates for 2026/27 rest on three checks: your plan (especially Plan 5 interest at RPI 4.1% for new England undergrads), the period cap on Plan 2 / Plan 3 (6%), and the fact that interest can still accrue below the repayment threshold. Lock personal numbers to GOV.UK and SLC — not to third-party summaries alone.
For free help with eligibility and applications:
Prefer to talk? Contact AF Education on 020 7377 8844 or info@afeducation.co.uk — we help UK home students with funded courses and SFE applications while you confirm interest and repayment figures on GOV.UK.